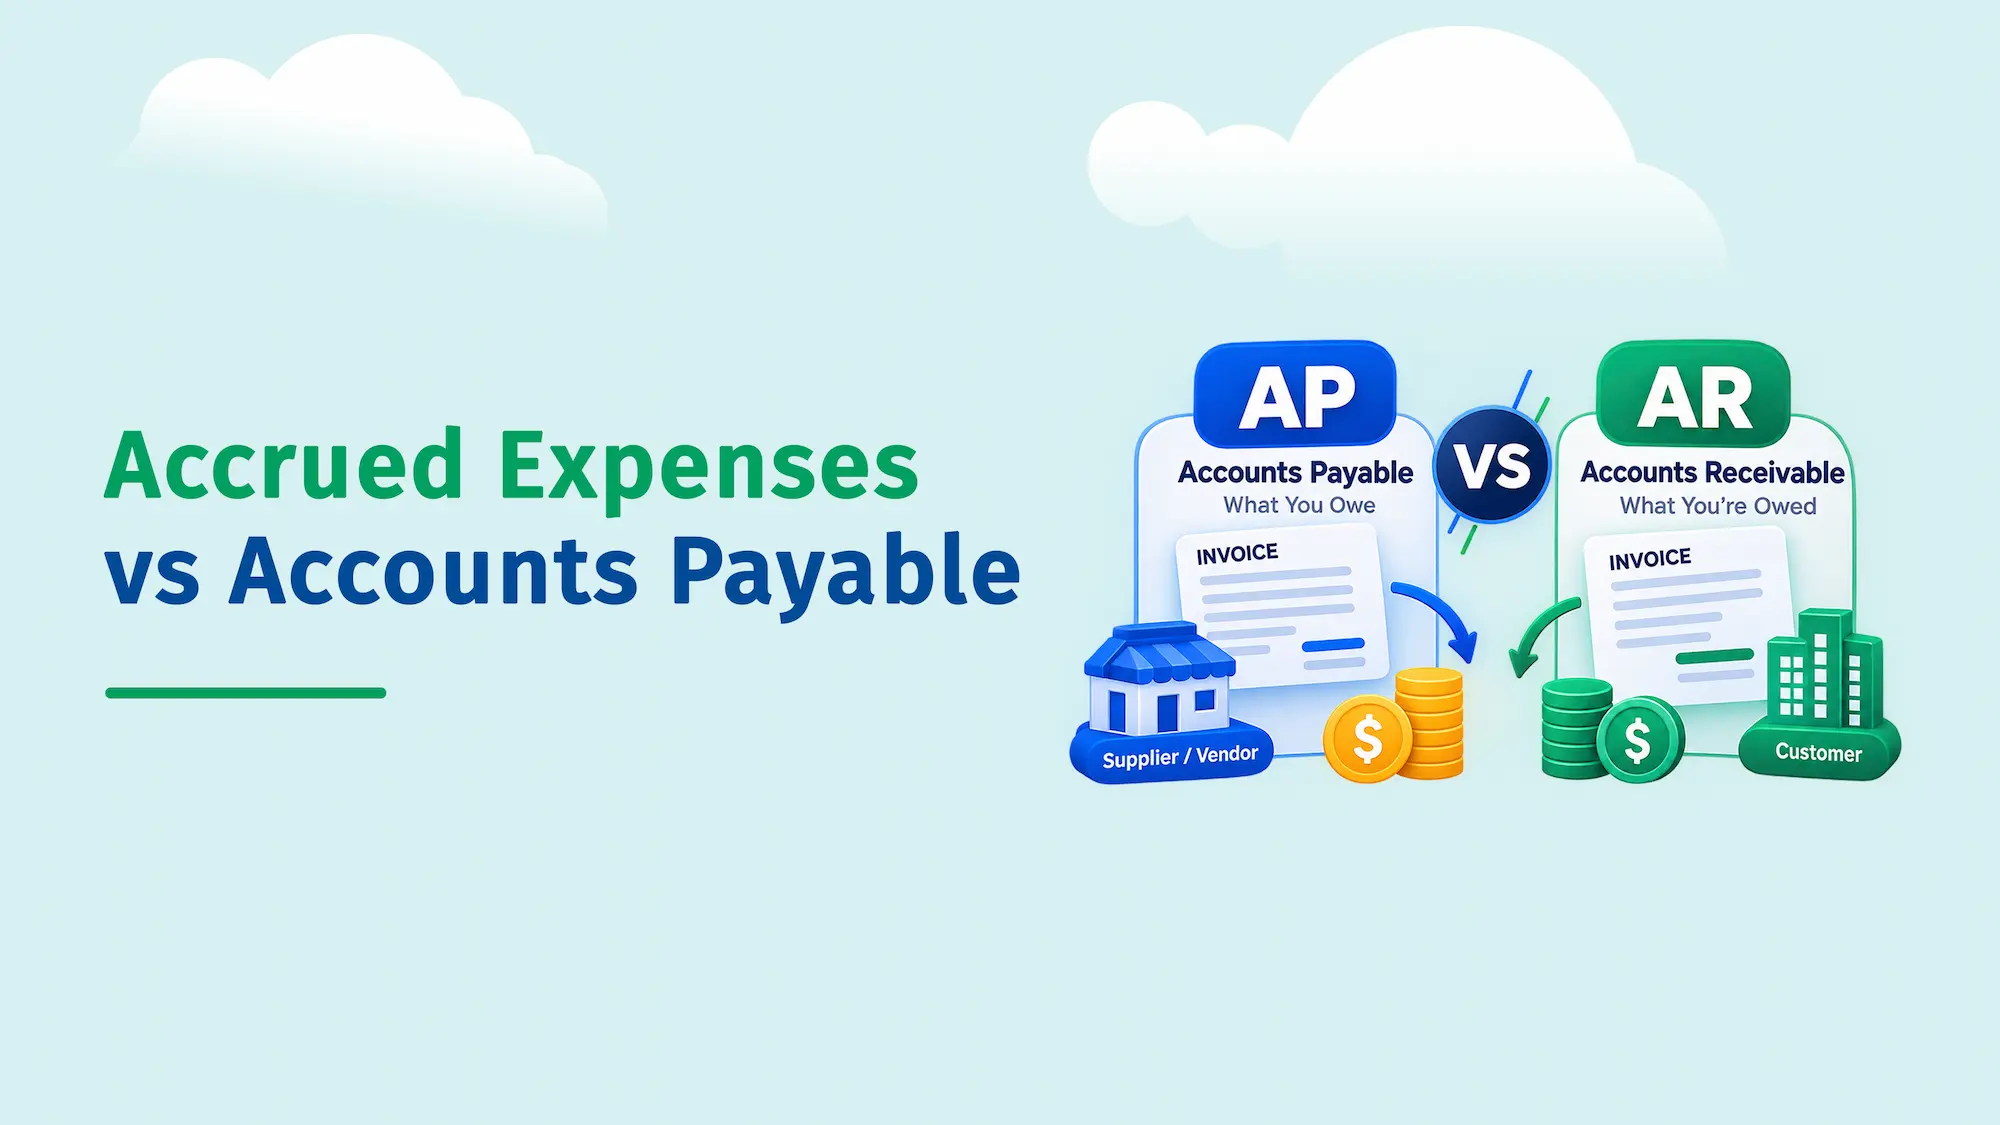
An accrued expense is a cost your business has already incurred but hasn't been invoiced for yet, so the amount is often estimated and recorded with an adjusting entry at period-end. Accounts payable is money owed to vendors on invoices that have been received and recorded. Both are liabilities, usually current ones.
A simple way to remember it: no invoice yet usually means accrued expense; invoice received and recorded usually means accounts payable. The invoice is a handy practical dividing line, but the real accounting question is when the cost was incurred and how your policies say to recognize it.
Accrued Expenses vs Accounts Payable: Quick Comparison
| Accrued expenses | Accounts payable | |
|---|---|---|
| What it is | A cost incurred but not yet invoiced or recorded in AP | An amount owed on a vendor invoice that has been received and recorded |
| Invoice received? | Usually no | Yes |
| Amount | Often estimated | Known from the invoice |
| When recorded | When the cost is incurred, often at period-end close | When the invoice is received and processed |
| Common examples | Wages, utilities, interest, taxes, unbilled services | Supplier invoices, contractor bills, inventory invoices |
| Typical owner | Accounting or controller | AP team |
| Balance sheet line | Accrued liabilities (current) | Accounts payable (current) |
| What happens next | Reversed or cleared when the actual invoice is recorded | Approved and paid on the invoice terms |
What Are Accrued Expenses?
An accrued expense is a cost your business has already taken on even though the bill or payment hasn't happened yet. Under accrual accounting, the cost belongs in the period you received the goods or services, not the period the bill shows up.
Say employees work the last three days of September, but payday is October 5. You still incurred that wage cost in September, so the September books should show it.
- Wages: pay earned but not yet paid
- Utilities: power, water, or gas used before the bill arrives
- Interest: interest built up on a loan but not yet due
- Taxes: payroll or other taxes owed for the period
- Professional services: legal, audit, or consulting work done before the invoice
- Goods received: supplies or inventory delivered before the supplier bills you
Because there's no invoice yet, the amount is often an estimate. Base it on real evidence: contracts, POs, receiving records, timesheets, usage data, or past invoices from the same vendor.
Example: accruing a consulting cost
A consultant does $5,000 of work in September and will invoice in October. On September 30:
| Account | Debit | Credit |
|---|---|---|
| Consulting Expense | $5,000 | |
| Accrued Expenses (liability) | $5,000 |
Accrued expenses vs accrued liabilities
Most people use these terms to mean the same thing. Strictly, the accrued expense is the cost you recognize, and the accrued liability is the balance sheet account that holds what you owe. Note that accruals only exist under accrual accounting. A business on cash-basis accounting records costs when it pays them.
What Is Accounts Payable?
Accounts payable is money your business owes vendors for goods or services that have been invoiced but not yet paid. The invoice gives you a known amount, a due date, and a vendor to pay. For the full picture of how AP works, see our guide to accounts payable.
Say a supplier delivers $10,000 of office equipment with an invoice due in 30 days:
Invoice recorded
| Account | Debit | Credit |
|---|---|---|
| Equipment | $10,000 | |
| Accounts Payable | $10,000 |
Invoice paid
| Account | Debit | Credit |
|---|---|---|
| Accounts Payable | $10,000 | |
| Cash | $10,000 |
Both accrued expenses and AP follow the normal liability rules: they go up with a credit and down with a debit. See accounts payable debit and credit rules if that feels backward.
The Invoice Test: Which Account Should You Use?
An accrual doesn't turn into AP just because time passes. It changes when the invoice arrives and is processed. That's why it helps to think of accrued expenses and AP as two stages of the same bill:
How an Accrued Expense Moves Into Accounts Payable
A manufacturer gets $20,000 of equipment maintenance on March 28. The invoice arrives April 4, and the company pays it April 30. It uses reversing entries.
| Date | Entry | Debit | Credit |
|---|---|---|---|
| Mar 31 | Accrue the expense | Maintenance Expense $20,000 | Accrued Expenses $20,000 |
| Apr 1 | Reverse the accrual | Accrued Expenses $20,000 | Maintenance Expense $20,000 |
| Apr 4 | Record the invoice in AP | Maintenance Expense $20,000 | Accounts Payable $20,000 |
| Apr 30 | Pay the invoice | Accounts Payable $20,000 | Cash $20,000 |
The reversal on April 1 and the invoice on April 4 cancel out, so April shows no net expense and March keeps the full $20,000. If the team forgot the reversal, April would show a second $20,000 expense and the accrual would sit on the balance sheet with nothing to clear it. That's the most common way accruals go wrong.
Reverse or Reclassify? Two Ways to Clear an Accrual
Method 1: Reversing entry
Reverse the accrual on day one of the next month, then record the invoice in AP as normal when it arrives.
Good for: recurring accruals. Many accounting systems post reversals automatically, so AP doesn't need to hunt for the matching accrual.
Method 2: Reclassify
When the invoice arrives, move the balance straight from accrued expenses to AP.
| Account | Debit | Credit |
|---|---|---|
| Accrued Expenses | $5,000 | |
| Accounts Payable | $5,000 |
Both work. Pick one per type of accrual and use it every time.
What If the Invoice Doesn't Match the Accrual?
Accruals are estimates, so the final invoice is often a little different. Say you accrued $5,000 for consulting and the invoice comes in at $5,300. The $300 difference is commonly recorded in the period the invoice arrives, treated as a change in estimate, but follow your own accounting policies for the specific transaction.
The important part is having a process to compare accruals with actual invoices. Large or repeated gaps mean the estimate needs better support, such as signed contracts, POs, receiving records, timesheets, usage reports, or billing history.
Are Accrued Expenses and Accounts Payable Both Liabilities?
Yes. Both are amounts the business owes and expects to settle. Both are generally current liabilities when they're expected to be settled within one year or the normal operating cycle. Read more on why accounts payable is a liability.
The difference is presentation. Accounts payable usually gets its own balance sheet line, while accruals are grouped as "accrued liabilities" or "accrued expenses and other current liabilities." Larger companies often split accruals further, such as accrued payroll, accrued interest, and accrued taxes.
How They Affect the Financial Statements
| Statement | Accrued expenses | Accounts payable |
|---|---|---|
| Balance sheet | Raise accrued liabilities when booked | Raises AP when the invoice is recorded |
| Income statement | Put the cost in the period it was incurred | Expense or asset recorded with the invoice, unless already accrued |
| Cash flow statement | No cash until paid; increases are added back in operating cash flow under the indirect method | Same: no cash until paid; increases are added back |
| Working capital | Reduce it (current liability) | Reduces it (current liability) |
If you only watch AP, you miss bills you already owe. Missing accruals make expenses look lower and working capital look stronger than they really are. How AP and AR together affect cash is covered in accounts payable vs accounts receivable.
Why Accrued Expenses Matter During Month-End Close
Invoices often arrive after the month you got the goods or services. If the team ignores those costs, September looks too cheap and October too expensive. A practical close routine:
- Review goods and services received but not yet billed
- Check open POs and receiving records
- Review recurring costs billed in arrears, like utilities and software
- Compare this month's activity with past invoices from the same vendors
- Book supported accruals and write down how each estimate was made
- Reverse or clear accruals according to your close policy
- Compare actual invoices with last month's accruals
This sits alongside accounts payable reconciliation as part of a clean close.
What Is Goods Received, Not Invoiced (GRNI)?
GRNI tracks goods you've received before the supplier's invoice is received or processed. Many ERP systems handle it automatically through a clearing account:
GRNI is essentially an accrual for goods tied to a PO. It's not the same as every accrued expense, since wages, interest, and taxes don't go through it. Old GRNI items are worth reviewing because they often point to a missing invoice, a pricing dispute, or a receipt booked twice.
Accrued Expenses vs Prepaid Expenses
These two are opposites, and they're easy to mix up:
| Accrued expense | Prepaid expense | |
|---|---|---|
| Timing | Benefit received first, paid later | Paid first, benefit received later |
| Type | Liability | Asset |
| Example | September utilities billed in October | A year of insurance paid upfront in January |
Common Mistakes With Accrued Expenses and Accounts Payable
1. Recording costs only when the invoice arrives.
Expenses land in the wrong month, and results swing for reasons that have nothing to do with the business.
2. Forgetting to reverse or clear the accrual.
The same cost is counted twice: once as the accrual and again as the invoice.
3. Treating every unpaid amount as AP.
Unpaid wages, interest, and many taxes are usually accrued liabilities, not vendor AP.
4. Unsupported estimates.
Auditors will ask how you got the number. Tie each accrual to a contract, PO, receipt, timesheet, or past invoice.
5. Losing the link between accrual and invoice.
When the invoice arrives, AP needs to know an accrual exists. A PO number or clear reference prevents double booking.
6. Running high-volume AP on email and spreadsheets.
Approvals, duplicate checks, and invoice status get hard to trust, which makes the accrual-to-invoice handoff messier.
Where AP Automation Helps, and Where It Doesn't
Deciding what to accrue, and how much, is an accounting judgment. Software doesn't make that call. Where automation helps is everything after the invoice arrives, which is also when the accrual gets cleared: capturing the invoice, extracting data, checking for duplicates, validating details, routing approval, tracking status, and keeping an audit record. Tracking accounts payable metrics like processing time also shows how quickly invoices reach the books after month-end.
How Quick Payable fits
Quick Payable is a Salesforce-native AP app. Invoices come in by email or upload, and AI OCR invoice processing extracts the data. Duplicates are flagged and rejected, approvals route to an assigned approver and escalate above that person's monetary limit, and every action is logged on the invoice. It manages the invoice side of AP. Your accounting team still decides which costs to accrue at month-end and books those entries under your close process.
Using Salesforce for Accounts Payable?
See how Quick Payable handles invoice capture, validation, and approvals inside Salesforce. Book a free demo. 15-day free trial, no credit card required.
The Simple Rule
Accrued expenses recognize costs already incurred before the invoice is available. Accounts payable tracks vendor invoices that have been received and recorded but not yet paid. Both are liabilities. A clean process connects them: recognize the cost when it's incurred, clear the accrual when the invoice is processed, then move the invoice through approval and payment. Final treatment should follow your accounting policies and the framework that applies to you, such as U.S. GAAP.
Frequently Asked Questions
No. Both are liabilities, but they are different stages of an obligation. An accrued expense is a cost already incurred but not yet invoiced or recorded in AP. Accounts payable is an invoiced amount that has been recorded but not yet paid.
In a typical workflow, when the vendor invoice is received and recorded. The accrual is then reversed or reclassified, depending on the company's process. Time passing alone does not change it.
Not in the usual sense. Both come from accrual accounting and both are unpaid obligations, but AP refers to invoiced vendor amounts and is tracked in a separate liability account.
Generally, yes, when they are expected to be settled within one year or the normal operating cycle. The exact presentation depends on the accounting framework and the company's circumstances.
They are opposites. An accrued expense means you received the benefit before paying, so it is a liability. A prepaid expense means you paid before receiving the benefit, so it is an asset until used.
Reversing the accrual at the start of the next period lets the actual invoice be recorded through the normal AP process without counting the expense twice. Many systems post reversals automatically.
The difference between the estimate and the actual invoice is reconciled and adjusted under the company's policies, commonly in the period the invoice arrives. Repeated large gaps mean the estimating method needs better support.
Goods Received, Not Invoiced (GRNI) tracks goods received against a purchase order before the supplier invoice is received or processed. It clears when the invoice is matched and recorded in AP.
AP automation manages the invoice side, such as capture, validation, approval, and tracking, once the invoice arrives. Deciding which costs to accrue at month-end remains an accounting task.
Shyam Agarwal is a technology professional with 12+ years of experience in Salesforce consulting, development, and administration. He writes about accounts payable, AP automation, and Salesforce, drawing on his experience delivering scalable technology solutions that support business needs and improve operational efficiency.